While artificial intelligence (AI) stocks have delivered explosive returns in recent years, none have kept pace with AXT (NASDAQ: AXTI) over the past year. The materials science company’s stock is up roughly 6,000% over the past year. This is largely because the wafer substrates it produces are vital for the AI boom.
Naturally, some investors feel like they missed out on the opportunity here, but the stock is still worth keeping an eye on. Here’s what investors should know about this highly volatile growth stock that has outpaced all of the others over the past year.
Will AI create the world’s first trillionaire? Our team just released a report on the one little-known company, called an “Indispensable Monopoly” providing the critical technology Nvidia and Intel both need. Continue »

AXT’s indium phosphide wafer substrates are next-gen technology for the AI boom
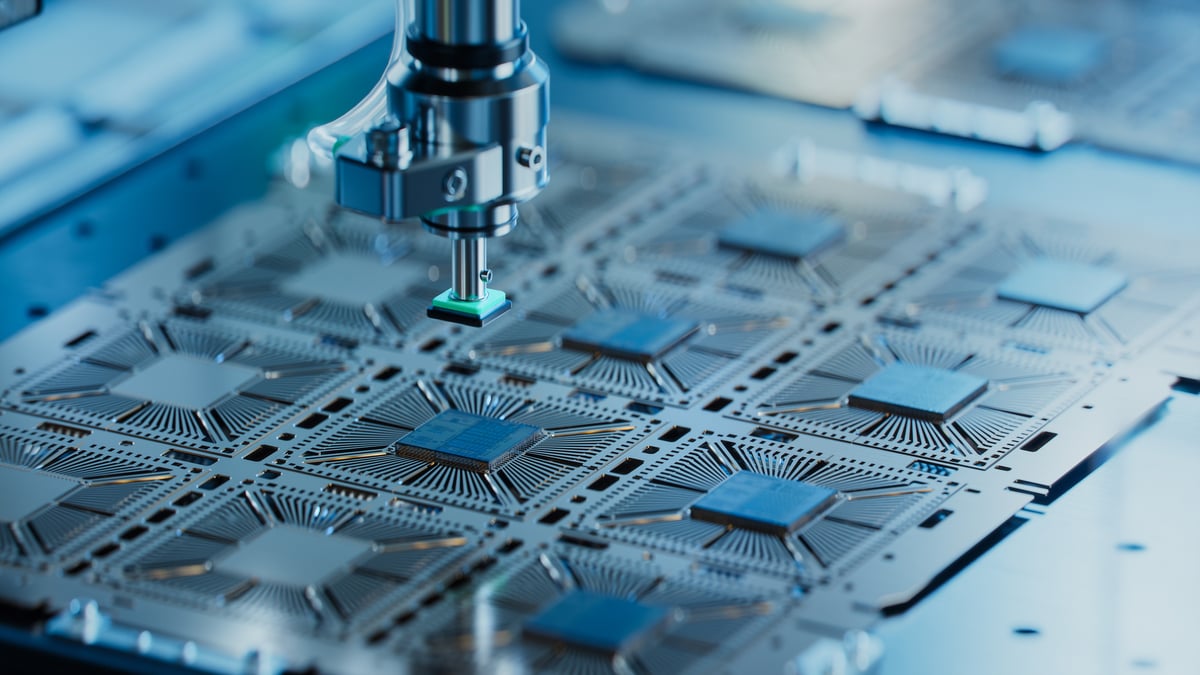
AXT makes semiconductor wafer substrates that include indium phosphide, gallium arsenide, and germanium, with the first material being the most important. Those semiconductor wafer substrates are the foundation for AI chips.
It’s not the only company that makes wafers, and Nvidia currently prioritizes the silicon wafers that Taiwan Semiconductor Manufacturing produces. However, those silicon wafers have limits that indium phosphide can exceed. The types of wafers AXT produces can handle more intense AI workloads than the silicon wafers currently found in most AI chips.
AXT and two other companies control approximately 80% to 90% of the indium phosphide wafer market. Indium phosphide wafers are more expensive than silicon wafers, which means a complete replacement is out of the question. However, these same wafers can move data faster while consuming less electricity, thereby reducing data center operational costs.
The risks are enormous
AXT’s substantial stock gains do not coincide with fundamental growth. Revenue decreased from $99.4 million in fiscal 2024 to $88.3 million in fiscal 2025. The company reported preliminary first-quarter 2026 revenue, saying it would come in between $26 million and $28 million. Annualized, that would definitely exceed the 2024 number.
That’s not a substantial leap, but AXT told investors in Q4 that its customer base has broadened to Tier-1 companies, which it had limited exposure to earlier in the year. Tier-1 companies refer to large global customers, but guessing which of those AXT has among its customers at this point would be speculation.
Furthermore, the company is still burning through cash as it expands. It reported $23.2 million in net losses last year and recently raised $550 million by diluting shareholders. The preliminary Q1 2026 results suggest that more net losses are on the way.